
Savings
The Best 5-Year CDs: Earn Up to 5.00% and Lock It In to 2031

Top 5-year CD rates: 5.00% APY at Sallie Mae Bank, Popular Direct and Quorum Federal Credit Union (Bank Iowa also 5.00%, $50,000 minimum); 4.85% BTG Pactual; 4.82% CFG Bank; 4.80% E*TRADE; 4.75% Synchrony and Barclays. National average 1.78% (Bankrate, Oct 31); FDIC national rate 1.38% (September). Context: best 3-year CD about 4.85% and best 1-year about 4.75%; brokered 5-year CD 5.20%; top savings 4.34%–4.50%; 52-week T-bill 4.46%; I bond 5.51% (1.40% fixed); Fed funds 3.75%–4.00% with a December hike possible; inflation 3.7%. My arithmetic on $10,000 for five years: about $12,763 at 5.00% ($2,763 of interest) vs about $10,922 at the 1.78% average, a gap of about $1,841; after assumed 24% federal and 5% state tax the CD nets about 3.55% a year, about −0.15 points against 3.7% inflation; $12,763 is worth about $10,640 in today’s buying power before tax.
The comparison with the average is even starker. Bankrate’s survey put the national average five-year CD at about 1.78% on October 31. That means the best CDs pay almost three times as much as the typical one. This guide covers the top five-year rates, what they really earn after tax and inflation, what could go wrong if rates move and how to decide whether five years of lockup is right for your money.
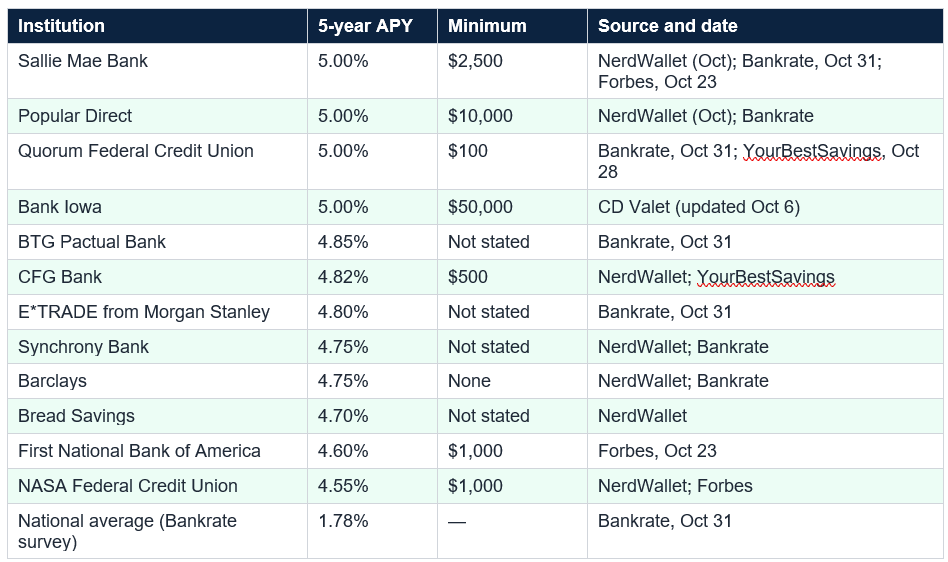
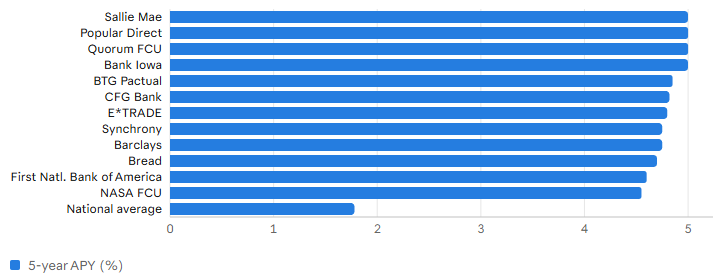
Five-year CD rates, October 2026: 5.00% at Sallie Mae Bank, Popular Direct and Quorum Federal Credit Union; 4.85% BTG Pactual; 4.82% CFG Bank; 4.80% E*TRADE; 4.75% Synchrony and Barclays. National average about 1.78% (Bankrate) or 1.38% (FDIC, September). Rates change daily.
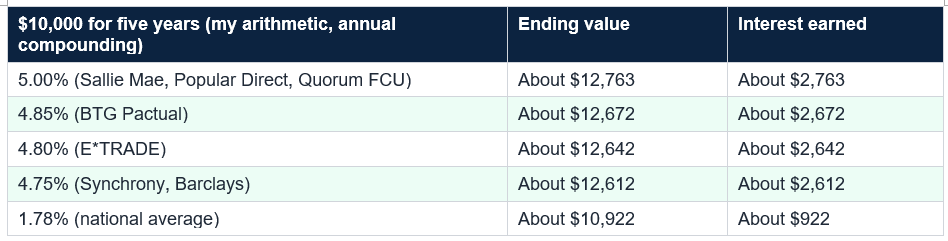
Notice how little separates the top rates and how much separates them from the average. The gap between 5.00% and 4.75% is about $151 on $10,000 over five years, while the gap between 5.00% and the average is $1,841. Shop for the best rate, but do not agonize over a quarter point at the cost of missing insurance, penalties or convenience. A rate is only as good as the institution and terms behind it.
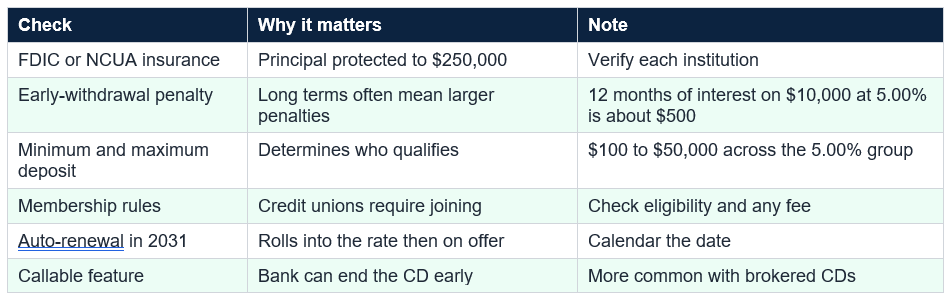
Fourth, eligibility: credit unions typically require you to join, sometimes through a small donation or an affiliation. Fifth, what happens at maturity in 2031: many CDs renew automatically at the then-current rate, so note the date and grace period. Sixth, whether the CD is callable, which means the bank can end it early if rates fall, a feature more common with brokered CDs than bank CDs. Finally, confirm the rate is fixed for all five years and that interest compounds as quoted.
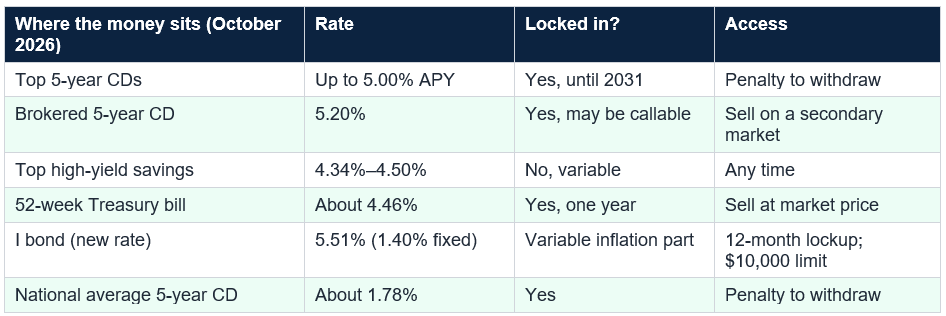
What each offers differs. A savings account offers access and flexibility but no guarantee its rate will last. A Treasury bill offers safety and a short lockup. An I bond offers inflation protection on top of a fixed rate. A five-year CD offers the longest guaranteed rate. With the Fed holding at 3.75% to 4.00% on October 28 and a December hike possible, it is a genuine bet on the direction of rates, so many savers split their money across several of these.
Over five years, the arithmetic compounds. $10,000 grows to about $12,763 before tax, but at 3.7% inflation that is worth about $10,640 in today’s buying power. After tax at the 24% and 5% rates, the money would grow to about $11,900, worth about $9,930 in today’s money, slightly less than you started with. A CD protects your principal and locks your rate, but it does not protect your purchasing power. Use it for safety and predictability, not for beating prices.
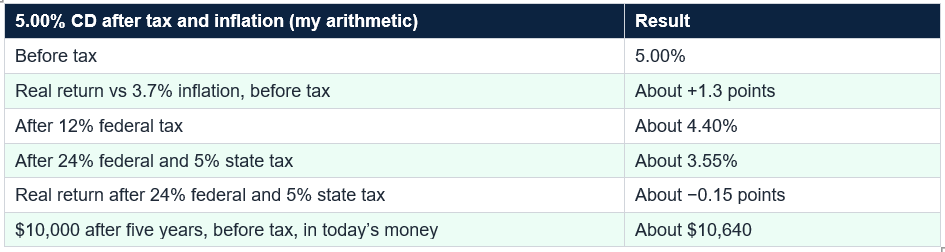
After tax, a 5.00% CD can earn less than 3.7% inflation. It is a tool for safety and a known return, not for growing your purchasing power. Consider tax-advantaged accounts for CDs if you can.
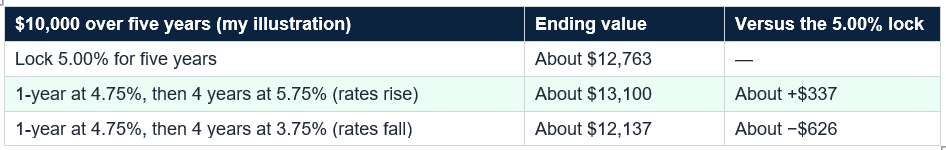
In other words, the lock-in wins if rates fall and loses if they rise, and the downside regret in my example is smaller than the upside protection. That is not a forecast. With the Fed on hold at 3.75% to 4.00% and a December hike possible, nobody knows. A lock-in is insurance against falling rates, with a price. If you value certainty, a five-year CD does the job. If you want to keep your options open, a shorter term or a ladder is the alternative.
Other ways to hedge include splitting money between a five-year CD and a high-yield savings account, using a barbell of short and long terms, or mixing in Treasury bills and an I bond. Bankrate found only 46% of Americans could cover three months of expenses, so before you lock any money for five years, make sure your emergency fund sits in an account you can reach. Money you might need in the next five years does not belong in a five-year CD.
It makes less sense if you might need the money, because the penalty can erase months or more of interest. It makes less sense if you think rates will rise, if you can get similar rates in more flexible places or if your goal is to beat inflation over many years, in which case a mix of stocks and inflation-protected bonds may serve better. This is general information, not personal advice, and your situation may differ.
Sixth, plan for taxes: you will receive a Form 1099-INT each year. Seventh, if you are depositing more than $250,000 or have other accounts at the same institution, spread money across institutions to stay within insurance limits. Eighth, consider a ladder for large sums. The process takes less than an hour, and then your money works quietly for five years.
Before you open a five-year CD, write down what the money is for, when you will need it and what the penalty would be. If you cannot answer all three, choose a shorter term or a ladder.
So use a five-year CD for what it does best: a guaranteed, known return on money you will not need until 2031. Check insurance, penalties and renewal terms, consider a ladder to reduce rate regret and keep your emergency fund somewhere flexible. In my illustration, locking in beat rolling one-year CDs by about $626 if rates fall and lost by about $337 if they rise. Rates change daily, so compare on the day you buy. This is general education, not personalized advice.
As of late October 2026, several institutions paid 5.00% APY on five-year CDs: Sallie Mae Bank ($2,500 minimum), Popular Direct ($10,000 minimum) and Quorum Federal Credit Union ($100 minimum), according to Bankrate and NerdWallet. Others paid 4.75% to 4.85%, including BTG Pactual, CFG Bank, E*TRADE, Synchrony and Barclays. The national average five-year rate was about 1.78%. Rates change daily.
Is a 5-year CD a good idea?
It can be if you will not need the money for five years and want a guaranteed return. A 5.00% CD turns $10,000 into about $12,763. But after assumed federal and state tax, it nets about 3.55% a year, a little below 3.7% inflation, and an early withdrawal can cost months of interest. It is best used for the stable part of your savings, not your emergency fund.
Why would I pick a 5-year CD over a 1-year CD?
Mainly to lock in today’s rate for longer. In late October, five-year CDs at the top paid 5.00%, slightly more than the best three-year (about 4.85%) and one-year (about 4.75%) rates. If rates fall, you keep 5.00%; if they rise, you are stuck. A ladder of different terms spreads that risk. This is general education, not personal advice.
Are 5-year CDs safe?
Principal is safe up to the insurance limit: FDIC-insured banks and NCUA-insured credit unions cover up to $250,000 per depositor, per institution, per ownership category. The risks are early-withdrawal penalties, inflation and the opportunity cost of being locked in. Check the insurance status of any institution before you deposit.
What happens if I need the money before five years?
You will usually pay a penalty, commonly expressed as several months of interest and sometimes a year or more on long terms. I did not retrieve the penalties for these institutions, so check each one. On $10,000 at 5.00%, a 12-month penalty would be about $500. Some banks offer no-penalty CDs, but at lower rates and shorter terms.
Table of Contents
- Why Five Years?
- The Short Answer
- The Best 5-Year CD Rates Right Now
- What 5.00% Really Earns
- What to Check Before You Lock In
- Five-Year CDs vs. the Alternatives
- The Catch: Inflation, Taxes and Opportunity Cost
- Rate Regret: What If Rates Rise or Fall?
- Laddering and Other Ways to Reduce the Risk
- When a 5-Year CD Makes Sense
- How to Open One Step by Step
- Conclusion
- Frequently Asked Questions
Top 5-year CD rates vs. the national average, October 2026 (APY %)
APY (%) by NerdWallet (Oct), Bankrate (Oct 31), Forbes (Oct 23), YourBestSavings (Oct 28), CD Valet; rates change daily; insurance status not verified
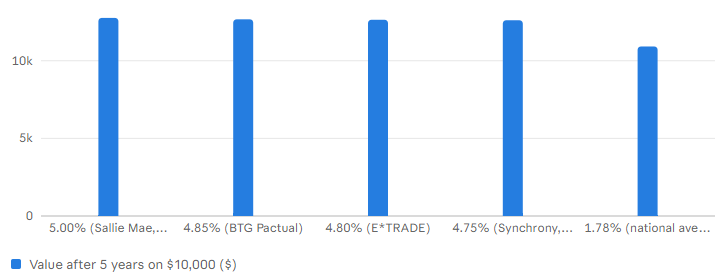
What $10,000 becomes in five years: top CD rates vs. the average ($)
Ending value ($) by Author's arithmetic, annual compounding of the quoted APY; 5.00% earns about $1,841 more than the average
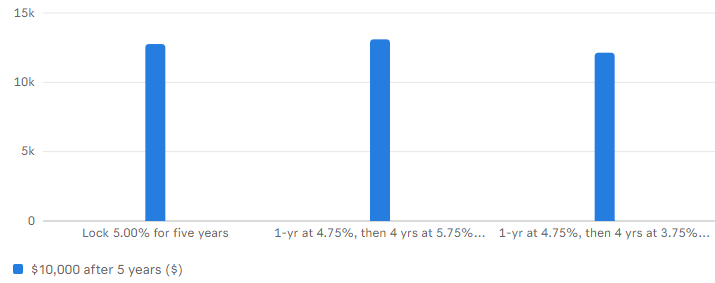
Rate regret: locking 5.00% vs. rolling one-year CDs as rates rise or fall ($)
Ending value ($) by Author's illustration, not a forecast: the lock beats rolling by about $626 if rates fall and trails by about $337 if they rise
Why Five Years?
A five-year CD is the commitment option. You hand over your money, agree not to touch it until 2031, and in return the bank promises a fixed rate for the whole time and the government insures your principal. For years, that bargain was not very exciting, because five-year CDs often paid less than shorter ones. In October 2026, it looks different: the top five-year CDs paid 5.00% APY, slightly more than the best three-year rates of about 4.85% and one-year rates of about 4.75%.The comparison with the average is even starker. Bankrate’s survey put the national average five-year CD at about 1.78% on October 31. That means the best CDs pay almost three times as much as the typical one. This guide covers the top five-year rates, what they really earn after tax and inflation, what could go wrong if rates move and how to decide whether five years of lockup is right for your money.
The Short Answer
The best five-year CDs in late October paid 5.00% APY at Sallie Mae Bank, Popular Direct and Quorum Federal Credit Union, with others at 4.70% to 4.85%, against a 1.78% national average. On $10,000, 5.00% grows to about $12,763 over five years. It is a strong, insured, fixed return, but not a free lunch: after assumed federal and state tax it nets about 3.55% a year, a hair below 3.7% inflation, and an early withdrawal can cost months of interest. A five-year CD suits money you will not need until 2031, ideally as one rung of a ladder, and only after your emergency fund is in place.The Best 5-Year CD Rates Right Now
Here are the leading five-year rates I found, with source and date. Three institutions pay 5.00%, but they differ in how easy they are to get: Quorum Federal Credit Union lists a $100 minimum, Sallie Mae Bank $2,500 and Popular Direct $10,000, and Bank Iowa also showed 5.00% with a $50,000 minimum and a $1,000,000 maximum on one listing. Credit unions generally require membership, and some of the rates come from smaller institutions you may not have heard of, so verify insurance first.Five-year CD rates, October 2026: 5.00% at Sallie Mae Bank, Popular Direct and Quorum Federal Credit Union; 4.85% BTG Pactual; 4.82% CFG Bank; 4.80% E*TRADE; 4.75% Synchrony and Barclays. National average about 1.78% (Bankrate) or 1.38% (FDIC, September). Rates change daily.
What 5.00% Really Earns
Here is the arithmetic, my own, using annual compounding of the quoted APY. On $10,000, a five-year CD at 5.00% grows to about $12,763, at 4.85% to about $12,672, at 4.80% to about $12,642, at 4.75% to about $12,612 and at 4.60% to about $12,522. At the 1.78% national average, the same $10,000 would reach only about $10,922. So a 5.00% CD earns about $1,841 more than an average one on $10,000. On $25,000, five-year interest at 5.00% is about $6,907, and on $50,000 about $13,814.Notice how little separates the top rates and how much separates them from the average. The gap between 5.00% and 4.75% is about $151 on $10,000 over five years, while the gap between 5.00% and the average is $1,841. Shop for the best rate, but do not agonize over a quarter point at the cost of missing insurance, penalties or convenience. A rate is only as good as the institution and terms behind it.
What to Check Before You Lock In
With five years of your money at stake, the fine print matters more than usual. First, insurance: FDIC-insured banks and NCUA-insured credit unions cover up to $250,000 per depositor, per institution, per ownership category, and YourBestSavings notes the CDs it tracks carry that protection. Verify each institution on the FDIC or NCUA site. Second, the early-withdrawal penalty, which on long terms is often larger, sometimes a year of interest or more. I did not retrieve these banks’ terms, so read them. Third, the minimum: $100 at Quorum, $2,500 at Sallie Mae and $10,000 at Popular Direct.Fourth, eligibility: credit unions typically require you to join, sometimes through a small donation or an affiliation. Fifth, what happens at maturity in 2031: many CDs renew automatically at the then-current rate, so note the date and grace period. Sixth, whether the CD is callable, which means the bank can end it early if rates fall, a feature more common with brokered CDs than bank CDs. Finally, confirm the rate is fixed for all five years and that interest compounds as quoted.
Five-Year CDs vs. the Alternatives
A five-year CD competes with several other places to put cash. Top high-yield savings accounts paid 4.34% to 4.50% in mid-October, a little less than the best CDs but with full access and a variable rate. A 52-week Treasury bill yielded about 4.46%, with state-tax-exempt interest. Brokered CDs showed 1-year 4.60%, 2-year 4.95% and 5-year 5.20% in mid-October. The new I bond pays 5.51% with a 1.40% fixed rate, but with a $10,000 annual limit and a 12-month lockup. The 10-year Treasury yielded about 5.24% in one mid-October reading.What each offers differs. A savings account offers access and flexibility but no guarantee its rate will last. A Treasury bill offers safety and a short lockup. An I bond offers inflation protection on top of a fixed rate. A five-year CD offers the longest guaranteed rate. With the Fed holding at 3.75% to 4.00% on October 28 and a December hike possible, it is a genuine bet on the direction of rates, so many savers split their money across several of these.
The Catch: Inflation, Taxes and Opportunity Cost
A 5.00% rate looks generous until you subtract what you give up. Inflation was 3.7% in September. Before tax, a 5.00% CD earns a real return of about 1.3 percentage points. After tax, it is thinner: CD interest is generally taxed as ordinary income federally and by most states, every year as it accrues, and I describe that as general knowledge, not retrieved from the sources above. In my illustration, at an assumed 24% federal and 5% state rate, 5.00% nets about 3.55%, which is about 0.15 points below inflation. At a 12% federal bracket it nets about 4.40%, a real gain of about 0.7 points.Over five years, the arithmetic compounds. $10,000 grows to about $12,763 before tax, but at 3.7% inflation that is worth about $10,640 in today’s buying power. After tax at the 24% and 5% rates, the money would grow to about $11,900, worth about $9,930 in today’s money, slightly less than you started with. A CD protects your principal and locks your rate, but it does not protect your purchasing power. Use it for safety and predictability, not for beating prices.
After tax, a 5.00% CD can earn less than 3.7% inflation. It is a tool for safety and a known return, not for growing your purchasing power. Consider tax-advantaged accounts for CDs if you can.
Rate Regret: What If Rates Rise or Fall?
The biggest question with a five-year CD is what happens if rates move. Here is an illustration of my own. Suppose you lock $10,000 at 5.00% for five years and end up with about $12,763. Now suppose you instead took a one-year CD at 4.75% and then rates rose one point, so you could earn 5.75% for the next four years. You would end up with about $13,100, about $337 more. But if rates fell by a point instead, to 3.75%, you would end with about $12,137, about $626 less than the five-year lock.In other words, the lock-in wins if rates fall and loses if they rise, and the downside regret in my example is smaller than the upside protection. That is not a forecast. With the Fed on hold at 3.75% to 4.00% and a December hike possible, nobody knows. A lock-in is insurance against falling rates, with a price. If you value certainty, a five-year CD does the job. If you want to keep your options open, a shorter term or a ladder is the alternative.
Laddering and Other Ways to Reduce the Risk
A CD ladder splits your money across terms. With $50,000, you might put $10,000 each in one-, two-, three-, four- and five-year CDs. Each year one matures, and you can spend it or reinvest it in a new five-year CD, so that eventually you hold five-year CDs maturing annually. A ladder gives you yearly access to cash, lets you capture today’s high rates and reduces the risk of locking everything in at the wrong time. At 5.00%, $50,000 would earn about $2,500 a year in interest.Other ways to hedge include splitting money between a five-year CD and a high-yield savings account, using a barbell of short and long terms, or mixing in Treasury bills and an I bond. Bankrate found only 46% of Americans could cover three months of expenses, so before you lock any money for five years, make sure your emergency fund sits in an account you can reach. Money you might need in the next five years does not belong in a five-year CD.
When a 5-Year CD Makes Sense
A five-year CD makes sense for money with a known long-term horizon: savings you will not touch until 2031, the stable part of a retirement portfolio, a long-term goal like a child’s education or a planned purchase years away. It suits people who value certainty, who think rates may fall and who have already built an emergency fund. It can also suit retirees who want a predictable return on part of their savings. The five-year CDs at 5.00% are at their highest in some time, which is itself an argument for acting.It makes less sense if you might need the money, because the penalty can erase months or more of interest. It makes less sense if you think rates will rise, if you can get similar rates in more flexible places or if your goal is to beat inflation over many years, in which case a mix of stocks and inflation-protected bonds may serve better. This is general information, not personal advice, and your situation may differ.
How to Open One Step by Step
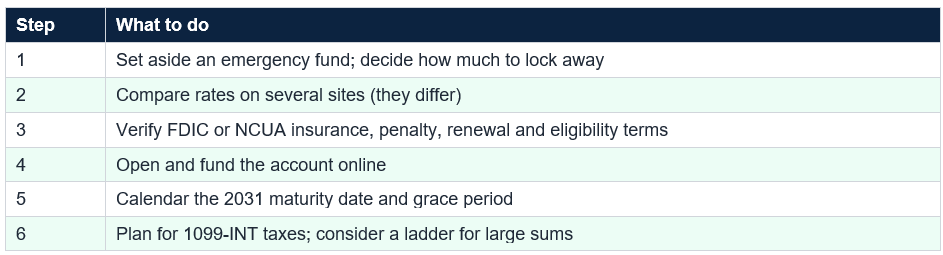
First, decide how much you can lock away for five years after setting aside an emergency fund. Second, compare rates on several sites, since the lists differ: Bankrate, NerdWallet, Forbes Advisor and rate trackers each highlight different leaders. Third, verify FDIC or NCUA insurance and read the penalty, renewal and eligibility terms. Fourth, open the account online and fund it by transfer. Fifth, note the maturity date in 2031 and the grace period, and decide in advance whether to withdraw, renew or move the money.Sixth, plan for taxes: you will receive a Form 1099-INT each year. Seventh, if you are depositing more than $250,000 or have other accounts at the same institution, spread money across institutions to stay within insurance limits. Eighth, consider a ladder for large sums. The process takes less than an hour, and then your money works quietly for five years.
Before you open a five-year CD, write down what the money is for, when you will need it and what the penalty would be. If you cannot answer all three, choose a shorter term or a ladder.
Conclusion
Five-year CDs are paying their best rates in some time: 5.00% APY at Sallie Mae Bank, Popular Direct and Quorum Federal Credit Union, with others at 4.70% to 4.85%, against a 1.78% national average. On $10,000, 5.00% grows to about $12,763, about $1,841 more than an average CD, with principal insured up to $250,000. But the real return is thinner than it looks: after assumed federal and state tax it nets about 3.55%, slightly below 3.7% inflation, and breaking the CD early can cost months of interest.So use a five-year CD for what it does best: a guaranteed, known return on money you will not need until 2031. Check insurance, penalties and renewal terms, consider a ladder to reduce rate regret and keep your emergency fund somewhere flexible. In my illustration, locking in beat rolling one-year CDs by about $626 if rates fall and lost by about $337 if they rise. Rates change daily, so compare on the day you buy. This is general education, not personalized advice.
Frequently Asked Questions
What are the best 5-year CD rates right now?As of late October 2026, several institutions paid 5.00% APY on five-year CDs: Sallie Mae Bank ($2,500 minimum), Popular Direct ($10,000 minimum) and Quorum Federal Credit Union ($100 minimum), according to Bankrate and NerdWallet. Others paid 4.75% to 4.85%, including BTG Pactual, CFG Bank, E*TRADE, Synchrony and Barclays. The national average five-year rate was about 1.78%. Rates change daily.
Is a 5-year CD a good idea?
It can be if you will not need the money for five years and want a guaranteed return. A 5.00% CD turns $10,000 into about $12,763. But after assumed federal and state tax, it nets about 3.55% a year, a little below 3.7% inflation, and an early withdrawal can cost months of interest. It is best used for the stable part of your savings, not your emergency fund.
Why would I pick a 5-year CD over a 1-year CD?
Mainly to lock in today’s rate for longer. In late October, five-year CDs at the top paid 5.00%, slightly more than the best three-year (about 4.85%) and one-year (about 4.75%) rates. If rates fall, you keep 5.00%; if they rise, you are stuck. A ladder of different terms spreads that risk. This is general education, not personal advice.
Are 5-year CDs safe?
Principal is safe up to the insurance limit: FDIC-insured banks and NCUA-insured credit unions cover up to $250,000 per depositor, per institution, per ownership category. The risks are early-withdrawal penalties, inflation and the opportunity cost of being locked in. Check the insurance status of any institution before you deposit.
What happens if I need the money before five years?
You will usually pay a penalty, commonly expressed as several months of interest and sometimes a year or more on long terms. I did not retrieve the penalties for these institutions, so check each one. On $10,000 at 5.00%, a 12-month penalty would be about $500. Some banks offer no-penalty CDs, but at lower rates and shorter terms.
0 Comments
Be the first to share your thoughts on this article.